Customs News
Customs Clearance Process: Do Buyer-Supplied Molds Belong in Customs Value?
07 Oct 2026 · 06:02 CET
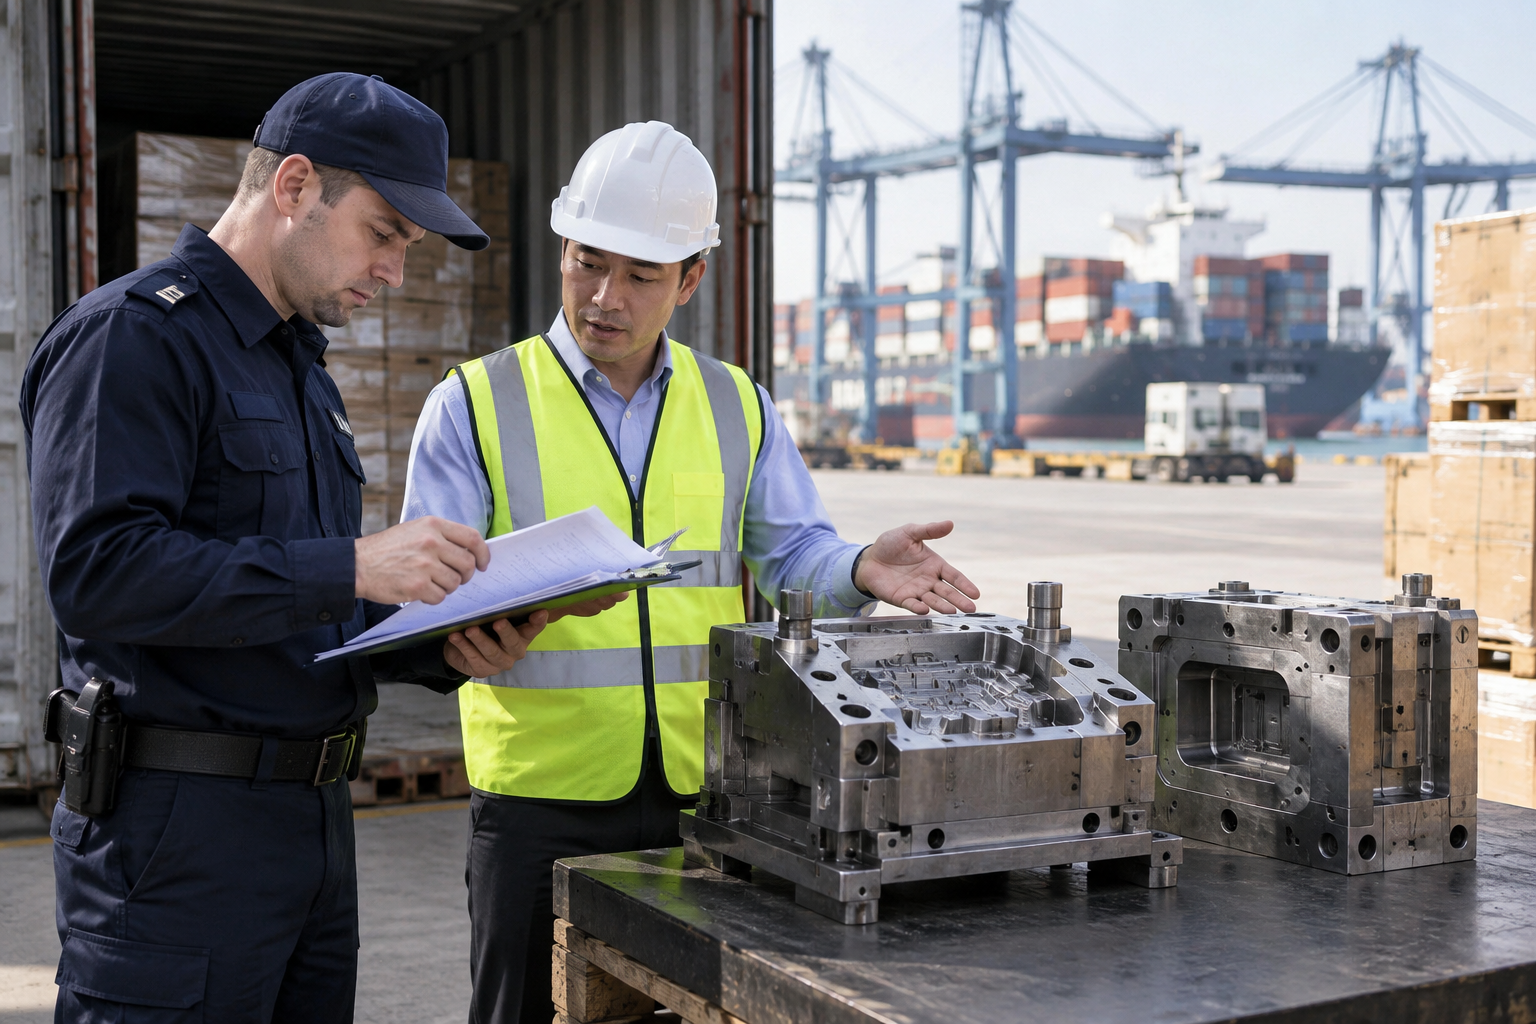
A reliable customs clearance process looks beyond the finished-goods invoice. If your business buys a mold separately and supplies it to an overseas manufacturer, some of that tooling value may belong in the customs value of the imported products—even when the manufacturer never invoices you for the mold.
The answer depends on the destination’s valuation rules, the applicable valuation method, the tooling arrangement and any amount already included in the goods’ price. The practical objective is to identify a required adjustment without adding unsupported costs or counting the same value twice.
Start with the tooling arrangement, not the invoice
Consider a hypothetical importer that commissions a mold from a toolmaker, pays for it and instructs the toolmaker to deliver it directly to an overseas factory. The factory uses the mold to manufacture products for that importer.
The finished-goods invoice lists only the unit price and quantity. The mold appears in purchasing and fixed-asset records, but not necessarily in the shipment paperwork.
That separation creates a valuation risk. A cost can sit outside the commercial invoice yet still be relevant to the value declared at importation.
Before the first shipment, purchasing should establish:
- Who purchased and paid for the mold.
- Who owns it and who may use it.
- Whether it was supplied directly or indirectly, free of charge or at a reduced cost.
- Which products and factories use it.
- Whether the goods price already includes any of the relevant tooling value.
Ownership is useful evidence, but it does not settle customs treatment by itself. The commercial substance of the arrangement matters.
Customs value vs invoice value: what changes?
Under a transaction-value approach, the starting point is generally the price actually paid or payable for goods sold for export to the importing country, subject to the applicable conditions and adjustments.
The invoice is important evidence of that price. It is not necessarily a complete valuation calculation.
For example, a buyer’s separate payment to the goods manufacturer for tooling may need examination as part of the price actually paid or payable, rather than automatically being treated as a distinct assist. A mold purchased from a third party and supplied to the manufacturer raises a different factual analysis.
Do not assume every tooling-related expense must be added. Equally, do not assume a separate purchase order or accounting classification excludes it from customs value.
Finance should identify the payment flows; the importer’s customs specialist or broker should assess their treatment. Keep these questions separate from whether the business capitalizes or expenses the mold in its accounts.
Review customs valuation assists
The WTO Customs Valuation Agreement provides an international framework. Under its transaction-value provisions, certain goods and services supplied by the buyer, directly or indirectly, free of charge or at reduced cost, for use in producing and selling imported goods for export can require an addition, appropriately apportioned, to the extent their value is not already included in the price actually paid or payable.
Tools, dies, molds and similar items used in production are among the categories covered by that framework. These contributions are commonly called assists.
However, the destination’s legislation, official guidance and relevant rulings determine how the framework applies to a particular import.
Confirm the method before calculating an addition
Before filing, the broker or customs adviser should review:
- Destination: Which customs authority’s rules govern the entry?
- Valuation method: Is transaction value available for this sale?
- Qualifying facts: Was the tooling supplied by the buyer for the relevant production and export arrangement?
- Existing inclusion: Is any of the same tooling value already included in the price actually paid or payable?
- Evidence: Can the value and allocation be supported with objective, quantifiable data?
If transaction value cannot be used, the importer needs a review of the applicable alternative valuation method. Adding a mold surcharge does not resolve that underlying issue.
Also distinguish the tooling’s physical location from its customs relevance. A mold that remains overseas may still affect the value of imported finished goods. If the mold itself crosses a border, that movement requires its own customs analysis.
Build an evidence file that follows the mold
The strongest file links the tooling purchase to the affected products and the proposed declaration calculation. A tooling invoice alone rarely explains the entire arrangement.
Purchasing: collect the commercial evidence
Before production shipments begin, purchasing should collect:
- Tooling purchase orders, contracts, invoices and payment records.
- Ownership, custody, transfer and permitted-use terms.
- Mold identifiers and the products manufactured with each mold.
- Delivery records showing where the tooling was supplied.
- Information about previous use, refurbishment or buyer-produced tooling, where relevant.
- Supplier confirmation of whether tooling value is included in unit prices, separate charges or credits.
Ask the supplier to explain how any included tooling amount is calculated. “Tooling included” is less useful than a clear breakdown linked to products and quantities.
Finance: reconcile the valuation inputs
Finance should reconcile the proposed tooling value to the ledger and supporting payments before the broker prepares the entry.
The amount used for customs purposes may require more analysis than copying the asset’s book value. Purchased tooling, internally manufactured tooling and previously used tooling can present different questions. Transport to the production site and other associated costs also need review under destination rules.
Maintain one controlled worksheet linking each adjustment to its evidence. Identify unresolved items explicitly rather than inserting an unsupported estimate.
Document mold cost allocation for imports
Once the relevant tooling value is established, determine how it should be apportioned to the imported goods. Do not choose an allocation merely because it produces the lowest declared value for the first shipment.
Depending on the applicable rules and facts, allocation may involve the first shipment, production completed by the first shipment or anticipated production supported by contracts or firm commitments. Do not assume one approach is universally permitted. If the mold serves multiple products or export markets, document how that use affects the proposed allocation.
Finance proposes; the broker checks
Before entry submission, finance should document:
- The tooling value proposed for allocation.
- The products covered and the reason for the allocation basis.
- The production quantity or other denominator used.
- The evidence supporting that quantity.
- The resulting amount per unit or shipment.
- The process for tracking amounts declared and reviewing changed assumptions.
The broker or customs adviser should check the proposed treatment against destination guidance. The importer should approve the basis before authorizing filing.
Illustrative calculation—not a universal rule
For an accepted unit-based allocation, divide the supportable tooling value by the approved production quantity to determine the tooling amount attributable to each unit. Multiply that amount by the relevant shipment quantity to calculate the shipment’s allocated tooling value.
If records establish that part of that same value is already included in the price actually paid or payable, reconcile the inclusion before calculating any separate addition. A supplier’s generic “tooling” charge does not, by itself, prove that the buyer-supplied mold’s value is included.
This illustrates the calculation sequence, not an approved method for every destination. Confirm that the value, denominator and treatment of existing inclusions are acceptable before using the result.
Prevent double counting before filing
Double counting can arise when a separate adjustment includes tooling value already accounted for in the price actually paid or payable. It can also arise when a broker repeats an addition after the relevant tooling value has already been fully allocated under the accepted method through earlier declarations.
However, a separate mold purchase and a supplier’s tooling charge are not automatically duplicates. They may cover different tools, services or payment obligations. Purchasing and finance should establish what each payment covers before the customs specialist determines the treatment.
Use a reconciliation showing:
- The total tooling value being considered.
- The portion of that same value already included in the price actually paid or payable.
- The separate adjustment, if required.
- The amount allocated through previous declarations.
- The remaining balance and affected products.
Supplier recovery schedules and customs allocation schedules may differ. Finance should explain that difference rather than assuming one substitutes for the other. Do not deduct a supplier charge from the goods’ price merely because it is described as tooling.
If forecasts change, a mold moves factories or a contract ends early, finance and the customs specialist should reassess the allocation before the next affected filing. Do not automatically write off or redistribute the remaining customs amount without reviewing the rules.
Prepare the declaration and resolve uncertainty
The importer should give the broker the approved valuation worksheet and supporting records before entry submission. The broker should flag missing information early enough for a decision—not silently default to the invoice total. Using a broker does not remove the importer’s responsibility to meet applicable valuation obligations.
Pre-filing checklist
- Purchasing: Confirm tooling arrangements and supplier price inclusions before shipment.
- Finance: Complete and reconcile the allocation worksheet before declaration preparation.
- Broker or customs adviser: Check the method, additions and reporting treatment before filing.
- Importer’s authorized owner: Approve the valuation basis before submission.
- Compliance team: Retain the calculation, evidence and entry reference for the destination’s required recordkeeping period.
Where treatment remains uncertain, the compliance team should seek official guidance or a valuation ruling where available, preferably before the first affected import. Check whether the procedure can address the planned transaction and what information it requires. If an answer will not be available before filing, the importer and adviser should confirm any lawful provisional or other authorized procedure rather than use an unsupported value.
If earlier entries may have omitted relevant tooling value, compliance should promptly identify the affected entries and applicable correction, disclosure or refund procedures and deadlines. Address potential overpayments as well as underpayments. Do not offset an earlier error against a later shipment without an authorized basis.
This is an operational framework, not a destination-specific legal determination.
Frequently asked questions
Must every buyer-supplied mold be added to customs value?
No. Review the applicable valuation method, qualifying assist conditions, supportable value and any amount already included in the price actually paid or payable. A separate tooling purchase triggers a review, not an automatic addition of the full invoice amount.
How does import duty on tooling costs work?
Where tooling increases the customs value of finished goods, it can increase value-based duty on those goods. The result depends on the goods’ classification, duty treatment and destination rules. It does not necessarily mean the mold is being declared as a separate import.
Can tooling value be allocated across future imports?
Potentially, if the destination permits the proposed basis and the production assumptions are adequately supported. Have the broker or customs adviser review the method before filing, and monitor changes to quantities and contracts.
What if the supplier says tooling is already included?
Request a written breakdown identifying the amount, what it covers and the affected products. Finance should reconcile it to the tooling agreement and payments. The customs specialist should then verify whether the same buyer-supplied tooling value is already included before the importer decides that no separate addition is required.
Source with valuation evidence in mind
Tooling transparency starts before the first purchase order. Ask prospective manufacturers how they document mold ownership, separate tooling charges and costs recovered through unit prices.
Ready to source or expand your trade network? Visit IMEX Center to explore sourcing and business-listing options, and make tooling documentation part of your supplier discussions from the start.
Source or sell globally with IMEX Center
Browse verified suppliers →