Banking & Finance
Letter of Credit Process: Build Quality Checks Into the LC Before Issuance
06 Oct 2026 · 12:02 CET
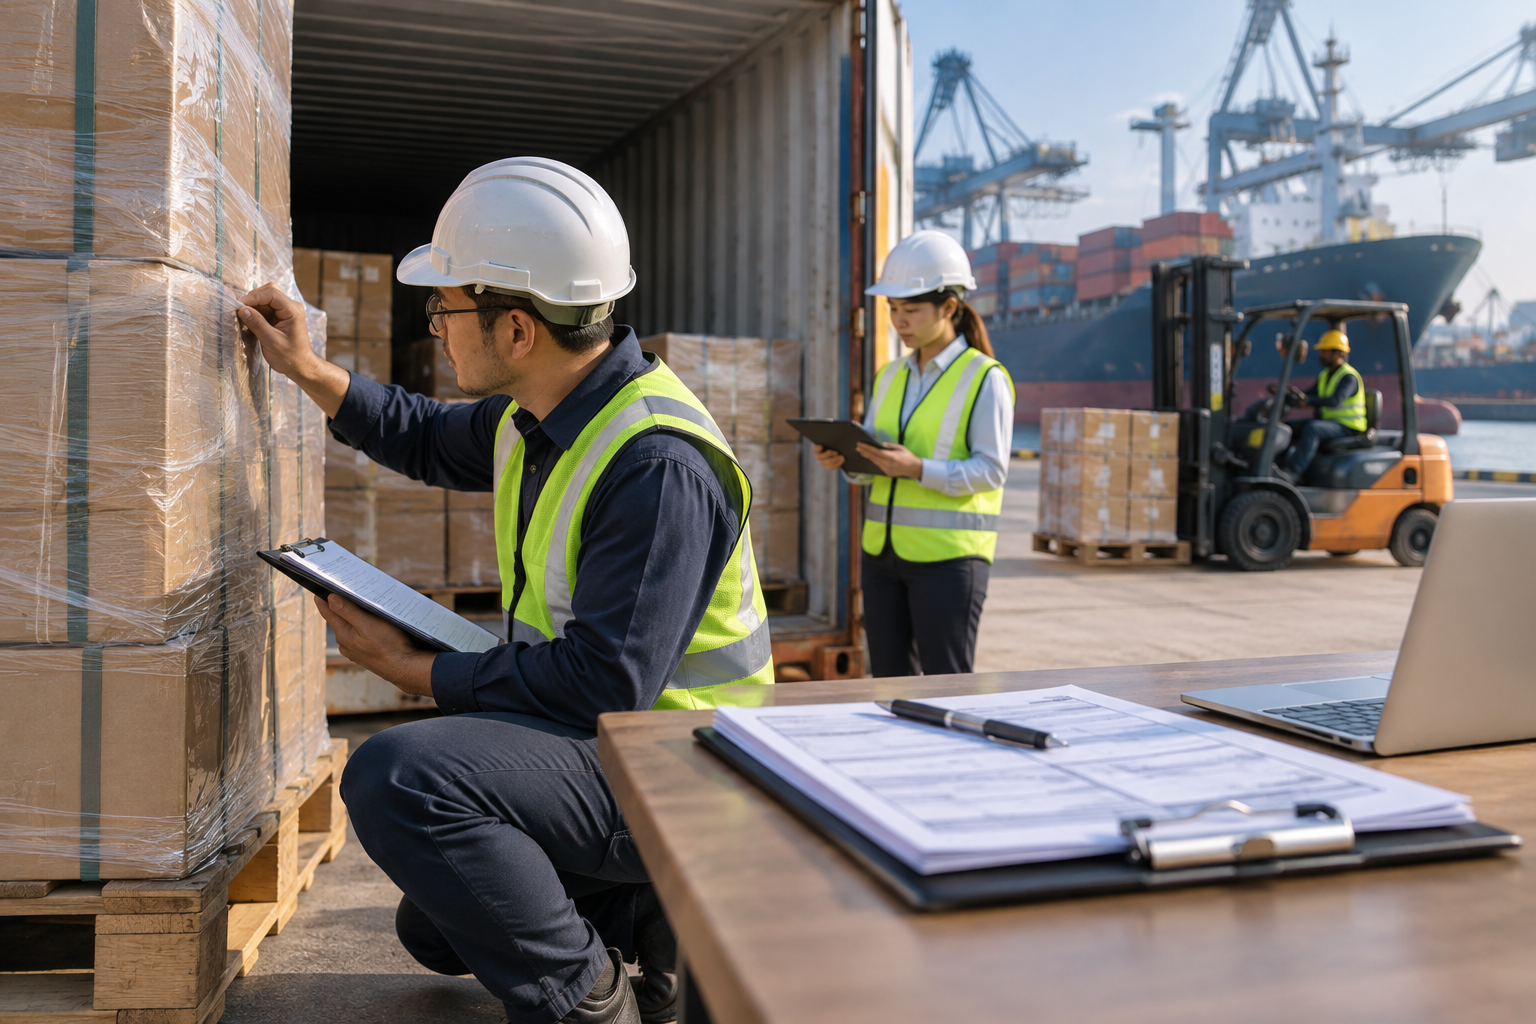
For importers, the letter of credit process should start with a quality-risk decision, not a bank application form. If payment must depend on independent inspection evidence, procurement, quality and treasury need to translate that requirement into documents the exporter can obtain and the bank can examine.
A letter of credit, or LC, does not guarantee that delivered goods will meet your expectations. The practical objective is narrower: require credible evidence that agreed checks occurred, while keeping warranty and defect remedies in the sales contract.
Understand the protection gap: documents are not goods
Under UCP 600, where those rules are incorporated into the credit, banks deal with documents rather than the goods, services or performance to which those documents relate. The credit is also separate from the underlying sales contract.
A complying presentation can therefore lead to honour under the LC even if the importer later discovers defects. Depending on the credit, honour may involve payment at sight, a deferred payment undertaking or acceptance of a draft payable at maturity. None of these arrangements turns the bank into a quality inspector.
Adding an inspection certificate creates a documentary gate. It does not make the issuing bank responsible for checking the cargo, repeating tests or guaranteeing that the certificate is accurate.
Owner and timing: Before agreeing payment terms, procurement and treasury should identify which quality risks need pre-shipment evidence and which require contractual remedies after delivery.
Start the letter of credit process with the purchase contract
Before signing the purchase order, procurement and quality should agree what acceptable goods look like. An inspector cannot reliably certify an undefined standard, and a bank cannot resolve a technical disagreement between buyer and seller.
Define the inspection scope and acceptance criteria
Use an agreed specification and inspection plan with identifiable versions. Depending on the product, these might address:
- Product model, materials, dimensions and performance requirements.
- Quantity, packaging, labels and shipping marks.
- Sampling method and defect acceptance criteria.
- Test methods, measurement tolerances and necessary laboratory work.
- Whether inspection covers finished goods, loading or both.
- The treatment of failed lots, reworked goods and repeat inspections.
Avoid replacing technical criteria with phrases such as “premium quality” or “to buyer satisfaction.” These invite disagreement and do not tell an independent inspector how to reach a result.
Keep commercial remedies in the contract
The sales contract should explain what happens when inspection fails: rework, replacement, reinspection, shipment postponement or another agreed remedy. Allocate the associated costs and address what happens if correction cannot be completed within the delivery schedule.
Separate warranty provisions should cover defects that an inspection cannot reasonably detect. Do not assume that passing inspection means the buyer must waive later claims.
Owner and timing: Quality defines measurable acceptance criteria; procurement incorporates them and the remedies into the contract before signature. Legal counsel reviews material warranty and dispute provisions where appropriate.
Agree how inspection will actually happen
A certificate requirement is only useful if the inspection provider can access the goods and issue the document on time. Before the LC application, the importer and exporter should agree the operational arrangements with the proposed provider.
Pre-application inspection checklist
Confirm:
- Provider: The issuing entity, its independence and relevant technical capability.
- Access: Who arranges factory access, sampling, testing and production records.
- Readiness: When goods must be completed, packed and available for inspection.
- Timing: Enough time for testing, certificate issuance and any permitted corrective work before shipment.
- Fees: Who pays inspection, laboratory, travel and reinspection charges.
- Document responsibility: Who orders the inspection and receives the certificate for presentation.
- Failure handling: How a failed inspection affects shipment readiness and the contractual delivery timetable.
If alternatives to the named inspector are needed, agree a clearly defined arrangement before issuance. “Any acceptable inspector” leaves the meaning of acceptable unresolved.
An LC requiring pre-shipment inspection should fit the production and logistics schedule. If required laboratory results cannot be available until after departure, change the inspection schedule or reconsider the documentary structure before issuing the LC.
Owner and timing: The exporter confirms access and readiness; the inspection provider confirms capability, document format and turnaround; procurement closes any gaps before treasury submits the application.
Specify a workable letter of credit inspection certificate
The LC should identify a document and the information it must contain. Keep detailed technical obligations in the contract and inspection plan, while requiring the certificate to state the relevant inspection outcome against those agreed references.
Why vague quality conditions fail
Consider this wording:
Goods must be satisfactory to the buyer before payment.
It neither defines satisfaction nor identifies a document evidencing compliance. For credits subject to UCP 600, Article 14(h) addresses conditions that do not stipulate a document to indicate compliance: banks treat such conditions as not stated and disregard them.
This is the practical significance of non-documentary conditions under UCP 600. A quality obligation written into an LC without a stipulated document indicating compliance may not provide the payment control the importer expects.
Requiring a buyer-issued approval certificate is different, but it can make payment dependent on the buyer's discretion. That may be unacceptable to the exporter. Prefer independent evidence against criteria agreed before issuance.
Illustrative documentary wording
The following is a discussion draft, not a ready-to-issue clause. Replace every placeholder and obtain bank, exporter and inspector review:
One original inspection certificate issued and signed by [agreed inspection entity], identifying purchase order [reference], the goods inspected, inspected quantities and applicable lot or batch identifiers. The certificate must state the inspection date, confirm that inspection was conducted before shipment in accordance with inspection plan [reference and version], and state that the inspected lot passed the acceptance criteria specified in that plan.
This wording assigns the technical conclusion to the inspector. It does not ask bank staff to interpret test readings or decide whether a product is suitable for its intended use.
The final wording must also reflect the inspection's actual scope. A sampling inspection should not be described as a guarantee that every unit is defect-free.
Certificate design checklist
Within the letter of credit document requirements, specify:
- The certificate's issuer and signature requirement.
- The required number of originals or copies.
- The inspection-plan reference and version.
- The required result statement and inspection date.
- Goods, quantity and lot identifiers that link the inspection to the shipment.
- How certificates cover partial shipments or multiple lots, if permitted.
Avoid requiring a final transport-document number on a certificate issued before that number exists. Use identifiers available at inspection, and agree how later shipment documents will establish the connection without conflicting data.
Run a three-way review before issuance
Before the issuing bank opens the credit, treasury should circulate the proposed documentary requirements to the bank, exporter and inspection provider. Each has a different responsibility; bank review alone cannot establish operational feasibility.
Treasury and issuing bank: check documentary workability
Ask the bank to review whether each inspection condition identifies the required document and evidence clearly. Check consistency with other LC terms, including shipment deadlines, expiry, presentation location and applicable presentation periods.
Clarify whether supporting test reports must also be presented. Requiring unnecessary documents creates additional opportunities for discrepancies without necessarily improving protection.
Exporter: confirm presentation feasibility
The exporter should confirm it can obtain the certificate and present it with the other stipulated documents within the LC timetable. Check that quantity descriptions, lot references and any permitted shipment tolerances can work together.
Avoid requiring word-for-word repetition across documents where consistent identification would suffice. Documentary data need not always be identical under UCP 600, but must not conflict with the credit or other stipulated documents when read in context.
Inspector: confirm it can certify the required facts
The provider should review the proposed certificate statements against its actual service scope. If it cannot certify a requirement, resolve that issue before issuance rather than assuming its standard report will satisfy the LC.
Owner and timing: Treasury owns the final pre-issuance checklist. Procurement resolves supplier issues, quality resolves inspection-scope issues, and the bank reviews documentary wording before issuance is authorised. If requirements change after issuance, treasury should coordinate any necessary LC amendment with the bank and obtain the required parties' agreement; changing the sales contract alone does not amend the credit.
Protect against the risks an inspection certificate cannot remove
Independent inspection can reduce uncertainty; it does not eliminate fraud, sampling limitations, latent defects, substitution after inspection or damage in transit. Banks do not guarantee a document's genuineness or the accuracy of its technical statements.
For safer importer payment terms, combine documentary controls with proportionate supplier due diligence and contractual protection.
Before contracting, procurement should agree warranty duration, defect-notification procedures, evidence requirements and available remedies. Quality should assess whether loading checks, seal records, retention samples or destination testing are justified by the product risk and agree any necessary arrangements before shipment.
Procurement should also agree a practical certificate-verification process with the inspection provider before issuance. Direct verification can support fraud controls, but do not assume the bank will perform it unless that service is expressly agreed.
FAQ
Does a letter of credit guarantee goods quality?
No. Banks examine the stipulated documents, not the goods. An inspection certificate can provide evidence of an agreed inspection outcome, but it does not replace warranties, supplier due diligence or remedies for defective goods.
Can an LC require independent pre-shipment inspection?
Yes. The parties can agree a requirement for an independently issued certificate. Before issuance, confirm the issuer, scope, result statements and identifiers, and ensure the exporter can obtain and present it within the credit's timetable.
What happens if the LC says only “goods must be satisfactory”?
For a credit subject to UCP 600, a condition without a stipulated document indicating compliance is disregarded under Article 14(h). Replace vague language with defined documentary evidence rather than relying on an unsupported quality statement.
Should payment depend on the buyer approving the inspection?
Generally, independent certification against agreed criteria provides a clearer structure than subjective buyer approval. Buyer-controlled approval documents may undermine the exporter's payment certainty and should not be introduced without explicit agreement and bank review.
Turn quality requirements into a sourcing decision
Choose suppliers that can support independent inspection, traceable shipment records and clear contractual remedies—not just attractive prices.
Ready to find trading partners? Source products or list your business on IMEX Center, and bring your inspection and documentary checklist into the discussion before agreeing LC terms.
Source or sell globally with IMEX Center
Browse verified suppliers →